A branded residence is a home sold with a hotel company's name on it, usually run by that company's staff and usually offered with a way to let it through the hotel. In Phuket the idea is not new. It is also concentrated in a few places, and on a price-per-square-metre basis it is the most expensive property on the island.
What is hard to find is what the premium pays for. Operators publish plenty about the lifestyle. Few publish the numbers a buyer needs: the rental split, the fees, the nights you can use the home yourself. This report sets out what they do publish, what our own catalogue shows about price and rent, and where the gaps are.
A disclosure first. Several of the listings quoted below are on our own book, and ZEN is paid by the seller when a property sells. That is a reason to check our figures, and every one of them is in the sources block.
What we counted, and what we left out
Our figures come from our catalogue on 17 September 2026: 2,552 priced, available listings, of which 699 are for sale. They are asking prices, not sale prices. Thailand has no public record of achieved prices, so nobody can tell you what a branded home actually sold for.
We counted a listing as branded only where the operator or developer names the brand on a page of its own that is still live today. That rule removed two groups that look branded and are not:
- Botanica Four Seasons is a phase of the Botanica development in Bang Tao, named after the seasons. It has nothing to do with Four Seasons Hotels.
- The Pavilions. Our book files seven villas under The Pavilions, but the operator's own residential-sales pages now redirect to its homepage. Without a live operator page, we left them out.
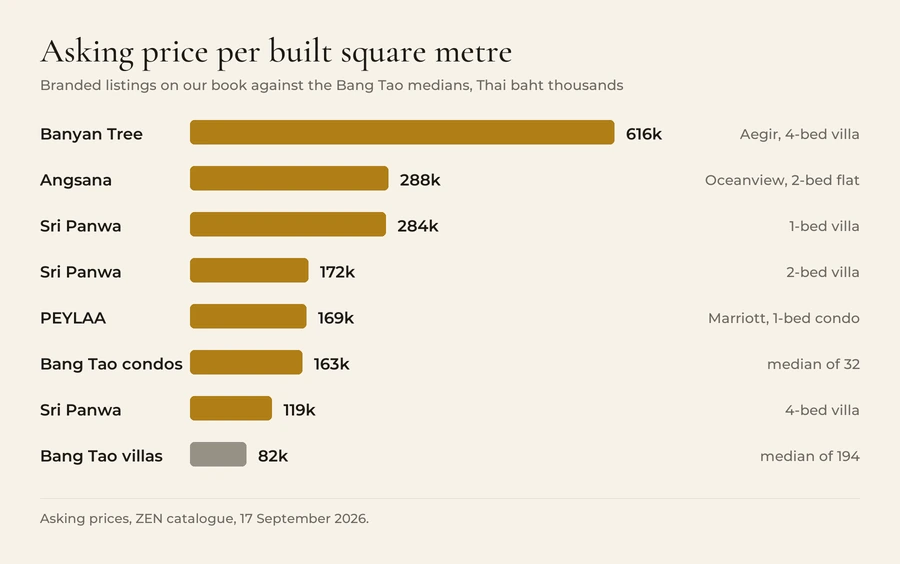
What remains is small: six sale listings, under 1% of our sale book, and five rentals. Six listings cannot support a median. So the table shows each branded listing on its own, next to Bang Tao medians drawn from hundreds of listings.
The headline: price per square metre
| Listing | Type | Built area | Asking price | Per m² |
|---|---|---|---|---|
| Banyan Tree Beach Residences Aegir, Laguna | 4-bed villa | 430 m² | ฿265.0m | ฿616,000 |
| Angsana Oceanview Residences, Laguna | 2-bed apartment | 278 m² | ฿80.0m | ฿288,000 |
| Sri Panwa, Cape Panwa | 1-bed villa | 140 m² | ฿39.8m | ฿284,000 |
| Sri Panwa, Cape Panwa | 2-bed villa | 320 m² | ฿55.0m | ฿172,000 |
| PEYLAA, Autograph Collection, Bang Tao | 1-bed condo | 45 m² | ฿7.6m | ฿169,000 |
| Sri Panwa, Cape Panwa | 4-bed villa | 1,600 m² | ฿190.0m | ฿119,000 |
| Bang Tao villas, unbranded | median of 194 | — | ฿27.0m | ฿82,000 |
| Bang Tao condos, unbranded | median of 32 | — | — | ฿163,000 |
The pattern is not a flat premium.
Beachfront Banyan Tree is in a class of its own. The Aegir villa asks ฿616,000 a square metre. That is 7.5 times the Bang Tao villa median, and 2.9 times the most expensive unbranded Bang Tao villa on our book, at ฿211,000. Banyan Group's own page for Oceanus, its newest beachfront scheme, publishes an average of roughly ฿375,000 to ฿426,000 a square metre, and prices from about ฿160m to ฿391m. So the Aegir listing is not an outlier within its own brand.
Branded apartments ask well above the median, but not beyond the market. The Angsana apartment asks 77% more per square metre than the median Bang Tao condominium. The most expensive unbranded condominium on our book still asks more, at ฿343,000.
Some branded units carry almost no premium. The PEYLAA one-bedroom, sold under Marriott's Autograph Collection name, asks within 4% of the Bang Tao condominium median. At Sri Panwa, price per square metre falls as the villa grows: the four-bedroom asks less per metre than any of the three other villas for sale in Cape Panwa on our book, which ask ฿141,000, ฿153,000 and ฿244,000. Three listings are too few for a median, so read that as a range, not a benchmark.
The research houses say the same thing more politely. Savills puts the global average brand premium at 33%, and 39% in resort destinations. Its Asia Pacific report puts the regional average at 29%, up from 23%, and names Phuket only as a destination. Neither report publishes a figure for Thailand or Phuket. Savills also warns that weaker projects "can easily underperform local comparables". Knight Frank says outright that the premium "is not guaranteed". If someone quotes you 33% as a Phuket number, they have taken a global average and moved it.
Where the branded schemes are
The search behind this article asks for the best areas for branded residences. The practical answer is that there are only a handful of them. Each place below is named by the operator or developer itself.
| Area | Schemes | Status, as the operator publishes it |
|---|---|---|
| Bang Tao / Laguna | Banyan Tree, Angsana, Cassia, Garrya, Laguna, Skypark, Bellaguna; PEYLAA (Marriott); Sri Panwa Lagoon | Banyan Group lists 20 schemes in Laguna Phuket; PEYLAA's hotel is expected to open in 2030 |
| Kamala | The Residences at InterContinental; MGallery and Twinpalms Residences at MontAzure; SLS Residences | InterContinental 13% complete on 28 August 2026; SLS expected in 2029, 13 villas from US$6.9m |
| Layan | Layan Residences by Anantara | Built; 15 pool villas on the sales site |
| Cherngtalay, Pansea | Trisara; Amanpuri | Resale only, as villas become available |
| Cape Panwa | Sri Panwa | Villas on sale; one series shows two different completion dates on the same page |
| Nai Harn | Wyndham Grand Nai Harn Beach | A 353-unit condo-hotel; the developer's sales text predates the 2020 opening |
Bang Tao is the deep market, as it is for unbranded property. We covered that in the best areas to buy in 2026. Kamala is the growth story, but most of it is not built yet. If you are buying off-plan, you are buying a completion risk as well as a brand. Current developments with live stock are on our projects page.
What the largest operator's own numbers show
Banyan Group is listed in Singapore, so it publishes what private developers do not: a sales table by project. Its 2025 annual report records 223 residences sold in Laguna Phuket for S$239.6 million. That is 27% less by value than in 2024. Its results briefing restates 2024 to exclude cancelled units, so the 2024 figures differ between the two documents. We have grouped the 2025 table by brand.
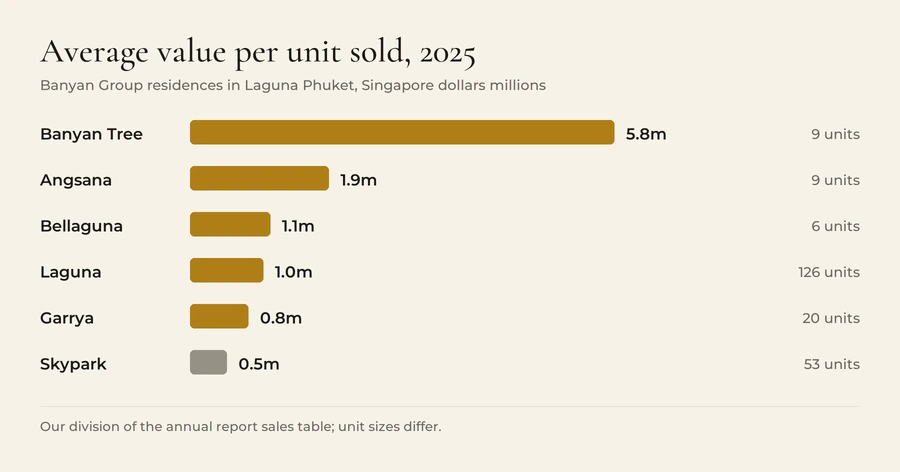
| Brand | Units sold, 2025 | Value, S$m | Average, S$m |
|---|---|---|---|
| Banyan Tree (Oceanus, Sirena, Nammu, Yara) | 9 | 52.2 | 5.80 |
| Angsana | 9 | 17.1 | 1.90 |
| Bellaguna | 6 | 6.4 | 1.07 |
| Laguna | 126 | 123.1 | 0.98 |
| Garrya | 20 | 16.6 | 0.83 |
| Skypark | 53 | 24.2 | 0.46 |
Banyan Tree made up 4% of the units and 22% of the value. The company calls the top segment slower-moving ("the inherently lower transaction velocity of this segment"). Its biggest seller was the mid-market Laguna Beach Residences Bayside, at 73 units. Russia was the largest source of buyers. Residences sales rose 38% in the first half of 2026, and the company says it expects to launch up to US$1 billion of new Phuket projects over the next two to three years. That last figure matters for resale: over the next few years, a Banyan Group owner may be selling against the company's own new stock.
What the brand does pay for
Most of what the operators publish falls under four headings.
- A management company that already exists. Angsana Oceanview's letting programme is run by the Angsana hotel next door. Banyan Group's newest beachfront owners are enrolled in its letting platform automatically.
- Owner nights. Angsana Oceanview publishes up to 60 days of personal use a year for owners in its letting programme. MGallery at MontAzure publishes 45 free nights. Sri Panwa advertises unlimited stays with no blackout dates on one of its villa types.
- A resale desk. Laguna Phuket runs one, and Trisara and Amanpuri sell their villas when owners release them. This is a real advantage in a market where resale is otherwise informal.
- Running costs that are sometimes published. Banyan Group quotes about ฿60 a square metre a month in common-area fees at Oceanus, plus a sinking-fund payment at transfer. It does not publish the amount. The InterContinental Residences publish a common fee of ฿120 a square metre and a sinking fund of ฿800 a square metre, but do not say what period the common fee covers.
What the brand does not pay for
A published return. Banyan Group publishes no revenue share, no guarantee and no management fee, either on its sales site or in its annual report. Its owner page says only that yields "vary by project". Sri Panwa publishes a 60% owner revenue share for one villa type. MontAzure publishes a "40/60 share model" for its MGallery units without saying which side takes the 60. The one guaranteed yield we found — 6% for two years at Wyndham Grand Nai Harn Beach — sits on a developer page written before the hotel opened in 2020. Ask for the current contract, not the brochure.
A rent premium to match the price premium. Our book carries two Angsana Oceanview two-bedroom apartments to let, at ฿250,000 and ฿260,000 a month on twelve-month leases. The Bang Tao median for a two-bedroom condominium or apartment is ฿100,000, from 37 listings. That is a large rent premium, but a smaller one than on price. Per square metre, the Angsana rents are about 1.5 times the Bang Tao median of ฿1,000 a month (56 listings). The Angsana sale listing asks 1.8 times the price median. Divide one by the other and the implied gross yield is about 6.1%, against about 7.4% for unbranded Bang Tao flats. That is a rough indication from a handful of units in two different pools of property, before any costs. It points in one direction, though: the brand lifts the price more than the rent. A Cassia two-bedroom on our book asks ฿80,000 a month, below the Bang Tao median, so the name alone does not guarantee a higher rent either. For how yields are built, see which Phuket areas actually deliver yield.
An evidence-based premium figure. Banyan Group's own owner page says branded wellness residences "command a 28% price premium". It gives no source or method. Treat it as marketing, as you would treat the same claim from anyone else, us included.
The legal points that decide whether a letting programme works
- Short lets need a hotel licence. Section 15 of the Hotel Act B.E. 2547 prohibits operating a hotel business without a licence, and Section 4 defines a hotel as temporary accommodation for payment. Stays paid monthly or longer are excluded. That is why Banyan Group requires lets of six months or less to go through its own platform, and why a hotel-run pool exists at all. A 2023 ministerial regulation exempts places with no more than eight rooms and thirty guests, but only after the owner has notified the registrar and received a receipt. The exemption is not automatic.
- The condominium foreign quota counts floor area, not units. Section 19 bis of the Condominium Act caps foreign ownership at 49% of the total unit area of the building. A branded condominium sold heavily abroad can run out of foreign quota even with units still unsold.
- Villas are usually leasehold for foreigners. Layan Residences by Anantara describes a "90 year leasehold ownership, comprising three successive 30 year terms". Only the first thirty years is a registered lease, as we explain in the 30-year leasehold, honestly. Price the first thirty years.
Five ways a branded purchase goes wrong
- Taking a name for a brand. A phase called Four Seasons is not Four Seasons. Find the operator's own page, and check that it is still live.
- Taking a licence for a promise. PEYLAA's own disclaimer says Marriott does not own, develop or sell the project and "has not confirmed the accuracy" of the developer's statements. That is normal for branded residences, and worth reading in full.
- Taking a global average for a Phuket number. The 33% belongs to Savills' global sample. There is no published Phuket premium.
- Reading an old page as a current offer. Guarantees and completion dates go stale. Sri Panwa's Sky Series page gives both Q4 2025 and December 2026.
- Letting the split go unwritten. Revenue share, owner nights, fees, the sinking fund and the terms for leaving the programme all belong in the contract you sign, not in a sales conversation.
Before you buy
- Find the brand on the operator's own site, and check whether the hotel is operating or only planned.
- Get the letting agreement: the revenue split, what is deducted before the split, owner nights and blackout dates, and the minimum term.
- Get the common-area fee, its period, and the sinking fund, in writing.
- Compare price per square metre with unbranded stock in the same district, and ask what the difference pays for.
- For a condominium, confirm the foreign quota still has room. For a villa, find out what is actually registered.
- Have your own lawyer check title and permits, as set out in due diligence on a Phuket villa.
A brand can buy you a working letting operation, a resale desk and a known standard of finish. It does not buy you a published return, and in Phuket it does not come with a published premium figure. Whether it is worth the money depends on which of those three things you will actually use. If you want to compare a branded scheme with unbranded stock at the same budget, tell us what you are looking for. The shortlist comes from the same book as these figures.