Phuket's villa market closed the third quarter of 2026 the way it spent September: with more houses on offer and almost nobody changing their price. On 29 September our book held 599 villas for sale, up from 543 on 3 September. Of the 540 that were listed on both dates, 538 were asking exactly what they asked four weeks earlier, and the other two had come down. The villa rental book did not grow at all, and 98.5% of the rentals that stayed on it kept their rent.
Everything else in this report follows from that. Medians that rose did so because of what was added, not because sellers asked more. Yields that fell did so for the same reason. And the official series — visitors, transfers, a regional house-price index and the policy rate — describe an island where demand slipped a little and the cost of money did not move.
What this report covers, and what it cannot
This is a villa report. Every figure from our own catalogue is restricted to listings typed as villas — 2,157 of the 2,580 priced, available listings on the book at the end of the quarter. Houses, condominium units, penthouses and townhouses are left out, which is why some numbers here differ from our monthly pulse, which counts every type.
It is also a quarterly report with one month of observed movement in it, and that needs saying first. Our database was loaded in a single day on 11 July 2026, and it keeps no price history. Nothing before that date records what a Phuket villa was asking, and nothing between 11 July and 3 September was saved either. Our dated snapshots begin on 3 September. So the "quarter" below is the state of the book on 29 September, the last snapshot inside Q3, compared where it can be with 3 September, the first. We would rather print one honest month than a reconstructed three.
The usual caveats hold. These are asking prices, not sale prices — Thailand has no public register of achieved prices, so nobody publishing Phuket figures has them, us included. Every median carries its listing count, and no slice below 15 listings is reported. A median also moves when the mix of listings moves, which is exactly what happened this quarter, so the like-for-like comparison comes before the medians.
The same villas, four weeks apart
| Villas to rent | Villas for sale | |
|---|---|---|
| On the book on 3 and 29 September | 1,520 | 540 |
| Same asking price | 1,497 | 538 |
| Price cut | 14 | 2 |
| Price raised | 9 | 0 |
| Left the book | 38 | 3 |
| New to the book | 38 | 59 |
The sale side is the striking column. Not one continuing villa seller raised their price over the month. Two cut: a Rawai villa from ฿16.0m to ฿15.8m, and a Pa Klok villa from ฿109m to ฿90m, a 17% reduction and the only large move on the whole sale book. The median of the 540 continuing villas is ฿21.9m on both dates.
On the rental side, 23 landlords out of 1,520 changed their asking rent, cuts slightly outnumbering rises, and the median of those continuing rentals is ฿150,000 a month at both ends of the month. As many villas arrived as left, 38 each, so the villa rental book finished the month at 1,558 listings — the same count it started with.
"Left the book" is the only honest label for the 41 departures. Some will have been let or sold, some withdrawn, and our catalogue does not record which. "New to the book" means new to us, not necessarily new to the market.
The sale book: bigger, and heavier at the top
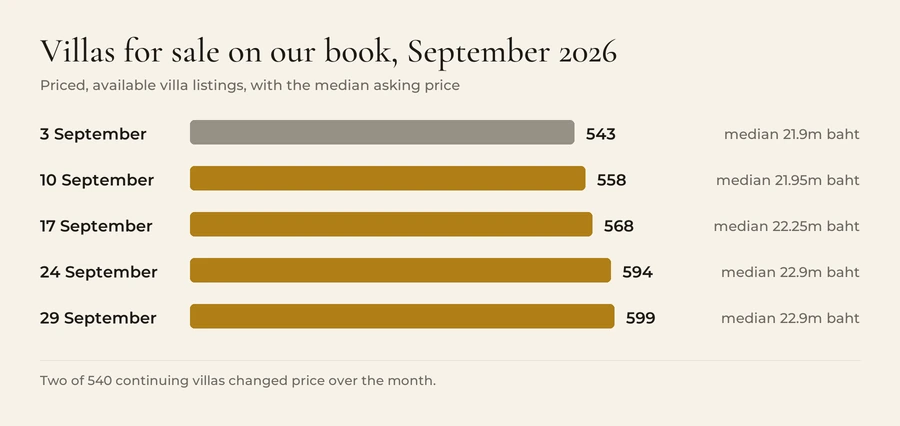
The villa sale book grew by 10.3% in four weeks, from 543 to 599 listings, steadily rather than in one batch. Its median asking price rose from ฿21.9m to ฿22.9m. That 4.6% rise is entirely composition: the continuing villas did not move, and the 59 that arrived have a median asking price of ฿27.0m. Thirty-seven of them ask ฿25m or more. None asks under ฿10m.
Bang Tao took 19 of the new listings, Rawai 14, Thalang 7 and Cape Panwa 6. The price bands show where the stock went:
| Asking price | 3 September | 29 September | Change |
|---|---|---|---|
| Under ฿10m | 16 | 16 | none |
| ฿10m to ฿20m | 234 | 246 | +12 |
| ฿20m to ฿40m | 190 | 215 | +25 |
| ฿40m to ฿80m | 63 | 72 | +9 |
| ฿80m and above | 40 | 50 | +10 |
Sixteen villas under ฿10m, on a book of 599, is the number a first-time buyer should take from this report. Our monthly pulse counts 86 sale listings under ฿10m across every property type, and the difference is the point: 70 of those 86 are condominiums, houses and other types, not villas, and the quarter added no villa at that price.
Price by size
| Bedrooms | Median asking price | Villas for sale | Median monthly rent, 12-month lease | Villas to rent |
|---|---|---|---|---|
| 2 | ฿13.6m | 49 | ฿90,000 | 134 |
| 3 | ฿18.95m | 264 | ฿125,000 | 737 |
| 4 | ฿28.8m | 178 | ฿180,000 | 459 |
| 5 | ฿49.0m | 77 | ฿250,000 | 154 |
| 6 | ฿75.0m | 19 | ฿290,000 | 39 |
The three-bedroom villa is the centre of both markets: 44% of the villas for sale and 48% of the villas to rent. Island-wide, the median villa for sale on 29 September asked ฿22.9m (599 listings) and the median villa let on a twelve-month lease asked ฿150,000 a month (1,545 listings). The step from four bedrooms to five is the steepest on the sale side, at 70%; on the rental side it is 39%. A fifth bedroom is priced as a different class of house when you buy it, and as a bigger version of the same house when you rent it.
Price per square metre, by district
| District | Median asking price | Per sq m | Median built area | Villas |
|---|---|---|---|---|
| Kamala | ฿84.0m | ฿104,600 | 650 sq m | 17 |
| Bang Tao | ฿27.0m | ฿82,500 | 383 sq m | 219 |
| Pa Klok | ฿26.2m | ฿66,400 | 410 sq m | 20 |
| Rawai | ฿16.9m | ฿65,100 | 300 sq m | 153 |
| Thalang | ฿21.0m | ฿63,600 | 343 sq m | 51 |
| Kathu | ฿19.65m | ฿63,300 | 396 sq m | 16 |
| Chalong | ฿16.95m | ฿59,600 | 300 sq m | 64 |
| Ko Kaeo | ฿16.0m | ฿59,600 | 300 sq m | 21 |
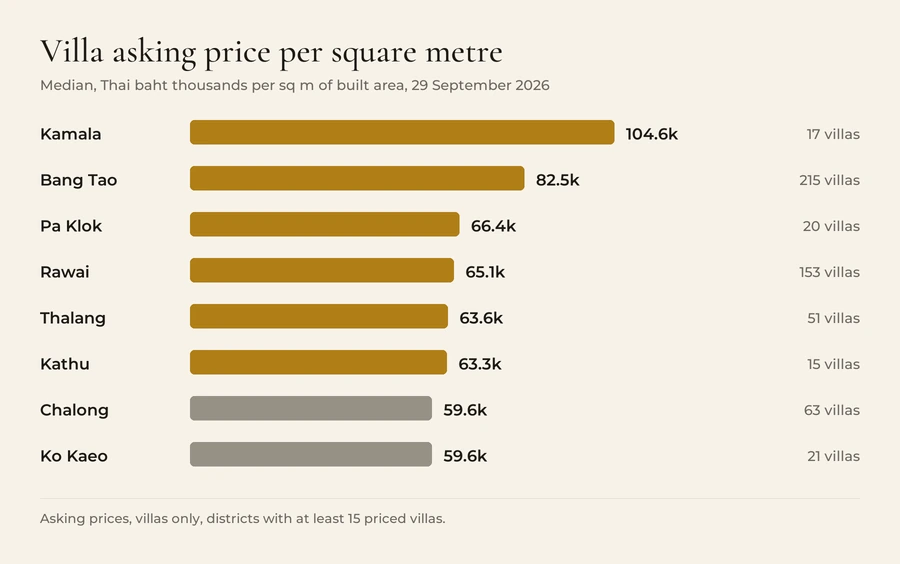
Across the whole villa sale book the median is about ฿72,400 per square metre of built area (593 villas that state one), against about ฿71,300 on 3 September (538). Per-metre figures use built area as the listing states it; we have not measured any house.
Two things stand out. The first is how flat the middle of the island is. Five districts — Pa Klok, Rawai, Thalang, Kathu, Chalong — sit within ฿7,000 a square metre of each other, and Ko Kaeo ties Chalong. A buyer who has ruled out the west coast is choosing between areas, schools and commutes, not between price levels.
The second is that the two dear districts are dear for different reasons. Bang Tao's premium is broad: 219 villas, a median build of 383 square metres, and more than a third of all the villas for sale on our book. Kamala's is narrow. Its 17 villas run from ฿12.9m to ฿816m, the median build is 650 square metres, and ten of the 17 ask ฿80m or more. Kamala's figure describes a handful of very large headland houses, and it would take only two or three listings to move it a long way in either direction. Read it as a pocket, not a district price.
Our Phuket property price index publishes per-metre figures on the same catalogue with its own method and frozen monthly editions; where the two differ, it is because the index is not restricted to villas.
Implied yield: still a bedroom question
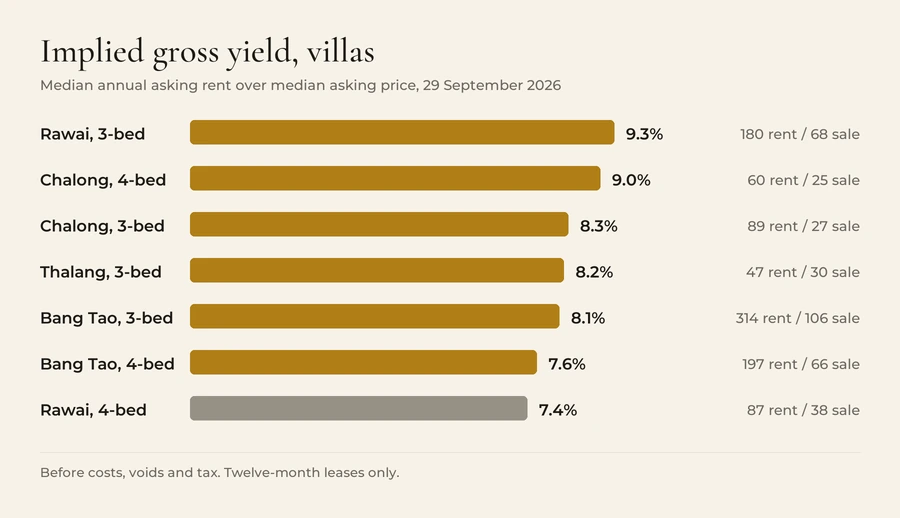
The method is the one we use everywhere: the median monthly asking rent for villas on a twelve-month minimum lease, times twelve, over the median asking price for villas with the same bedroom count in the same district, with at least 15 listings on each side. On 29 September, 1,545 of the 1,558 villa rentals on the book carried a twelve-month minimum, so annualising a monthly rent is a long-let figure and not a holiday-let one.
| District and size | 3 September | 29 September |
|---|---|---|
| Rawai, 3 bedrooms | 9.1% | 9.3% |
| Chalong, 4 bedrooms | 9.0% | 9.0% |
| Chalong, 3 bedrooms | 7.8% | 8.3% |
| Thalang, 3 bedrooms | 8.2% | 8.2% |
| Bang Tao, 3 bedrooms | 8.6% | 8.1% |
| Bang Tao, 4 bedrooms | 7.6% | 7.6% |
| Rawai, 4 bedrooms | 7.1% | 7.4% |
The pattern we described in September survived the quarter. Rawai is first at three bedrooms and last at four. Its strength is the family-sized rental; its larger houses ask sale prices the local rental market does not support. Chalong is the reverse, stronger at four bedrooms than at three. Any district yield quoted without a bedroom count has skipped this step.
Bang Tao's three-bedroom figure fell half a point in a month without a single landlord or seller in it changing price. Its median three-bedroom rent stayed at ฿150,000; its median three-bedroom asking price went from ฿20.95m (94 villas) to ฿22.25m (106) because the three-bedroom villas added over the month were dearer than the ones already there. Composition again.
These are gross figures on two different pools of houses. They come before management fees, maintenance, insurance, void months and tax, and before the gap between asking and achieved on both sides. They compare districts with each other honestly; they do not tell you what a particular villa will return.
The demand side: a full quarter of visitor data
The Ministry of Tourism and Sports' provincial file now covers September, so Q3 is complete. It counts foreign visitors staying in Phuket province, which is a different measure from border arrivals.
| Month | Foreign visitors, 2026 | 2025 | Change | Occupancy, 2026 | 2025 |
|---|---|---|---|---|---|
| July | 895,106 | 905,048 | −1.1% | 74.2% | 70.7% |
| August | 835,622 | 854,892 | −2.3% | 70.0% | 68.9% |
| September | 812,970 | 824,038 | −1.3% | 66.3% | 65.8% |
| Q3 | 2,543,698 | 2,583,978 | −1.6% |
Phuket received 2.54 million foreign visitors in the third quarter, 1.6% fewer than a year earlier, and 7.60 million over the first nine months, down 2.4%. Their spending, as the Ministry records it, fell by about the same amount over the quarter: ฿127.0bn against ฿129.1bn, down 1.6%. Every month's figure is marked preliminary.
The detail worth noticing is occupancy. All three months of the quarter were fuller than the same months of 2025, July by three and a half points, even with fewer foreign guests. Thai visitors made up part of the difference — up 5.6% in September — and the file does not break the rest down. We report it as the Ministry publishes it and do not try to explain it further.
We would not draw a line from these numbers to villa prices. A visitor count measures holidays; a twelve-month lease and a ฿23m purchase are different decisions made by fewer people. What the two series share this quarter is a temperature: slightly cooler than last year, and steady.
What the official housing data says
Transfers. The Real Estate Information Center's latest Phuket figures are still for the second quarter, published on 8 September: 1,905 second-hand homes transferred, worth ฿5,890m, up 4.8% in units on a year earlier, against 2,650 second-hand homes listed for sale, up 21.1%. Supply growing faster than sales is the same direction our book points. REIC's third-quarter second-hand release had not appeared when we checked on 22 October, and these figures cover every type of home, not villas alone.
Building costs. REIC's construction cost index for a standard house rose 1.5% in the third quarter and 2.1% on a year earlier, with structural work up 3.6% on the quarter and 6.2% on the year. The release summarises it, in our translation, as costs still rising while sale prices have limited room to follow. The index is measured in Bangkok, not Phuket, so treat it as the direction of a builder's bill rather than its size here.
House prices. The Bank of Thailand's residential price index has no Phuket series. Its southern-region single-detached-house index stood at 152.6 in June and July and 151.0 in August, on a 2011 base of 100; September had not been published when we checked. The Bank builds the index from mortgage-loan data reported by lenders, smoothed over three months, so it describes homes bought with a Thai mortgage, which a cash purchase from abroad is not. It is the closest official house-price series to the island, and it was flat to slightly down across the quarter.
Money. The policy rate was 1.00% for the whole quarter. The Monetary Policy Committee held it on 24 June and again on 26 August, unanimously both times, and its next scheduled meeting is on 28 October. For a buyer paying cash from abroad that is background; for the Thai developers building the new stock above, it is the cost of their money.
What it means
If you are buying. You have more choice than at the start of September and you are paying the same for it. On our book, villa sellers neither cut to find a buyer nor raised their asking price; two of 540 moved, both down. That makes the asking price a starting point rather than a signal, and a reasoned offer below it a normal conversation. The new choice is concentrated above ฿20m. Below ฿10m there are 16 villas on our book, as there were a month earlier, so a buyer with that budget should look hard at houses or at the cheaper districts' three-bedroom stock, and should not expect the quarter's new supply to help.
If you are renting. The villa rental book is the same size and the same price it was at the start of September, going into the high season. The leverage is in the terms — lease length, deposit, what is included — rather than the headline rent.
If you are selling. The competition grew by roughly one villa in ten in four weeks, most of it priced above the median, and the sellers already on the market have shown no appetite for moving their price. A villa listed now is compared with a bigger book than it would have been in August, and it will be compared at its first price for a long time.
If you are buying to let. Pick the bedroom count before the district. Three bedrooms in Rawai and four in Chalong head the gross figures; four in Rawai and four in Bang Tao trail them. A yield that moved half a point in Bang Tao this quarter without anyone changing their price is a reminder that a median-based yield is a comparison between districts, not a forecast.
Since the quarter ended. On 22 October, the date of this report, the book held 600 villas for sale at the same ฿22.9m median and 1,550 villas to rent. The stock that arrived in September has stayed, and the inflow has slowed to a single net listing in three weeks.
A fourth-quarter edition on the same method, against these snapshots, would be the first able to compare a full quarter with the one before it. In the meantime, browse what is available now, look through the projects behind the new listings, or compare the districts side by side. The month-by-month view, which counts every property type, is in our October market pulse.