Two things happened on our book in October, and they point in opposite directions. The homes that were already for sale or to let did almost nothing: of 1,823 rentals listed on both 5 October and 5 November, 1,819 ask exactly the same rent, and of 730 continuing sale listings, 724 ask the same price. Meanwhile the sale side grew by more than half in a week, as 396 units in developers' projects joined it, and the median asking price for a Phuket home on our book jumped from ฿19.9m to ฿24.55m.
That jump is real arithmetic and it is not a price rise. Nobody who was selling in early October cut their price over the month, and only six raised it. What changed is what is on offer, and for a buyer that matters more than the median does.
What we are counting
These figures come from our own catalogue: every listing that is available, priced and visible to the public. On 5 November 2026 that is 2,955 listings: 1,829 long-term rentals and 1,126 for sale. Villas are 85% of it; the rest is houses, townhouses, a few condominium units and penthouses. We compare against our snapshot of 5 October, with the same filter, the same 15-listing floor for any district figure and the same price bands as the October issue.
The usual two caveats apply. These are asking prices, not recorded sales: Thailand has no public sold-price register, so nobody publishing Phuket data has transaction prices, us included. And a median moves when the mix of listings moves, not only when prices do. This month the second caveat is most of the story, which is why the like-for-like check comes first.
The same homes, a month apart
| Rentals | For sale | |
|---|---|---|
| On the book on both dates | 1,823 | 730 |
| Same asking price | 1,819 | 724 |
| Price cut | 3 | 0 |
| Price raised | 1 | 6 |
| Left the book | 25 | 2 |
| New to the book | 6 | 396 |
Four rentals in 1,823 changed their asking rent. Two of the three cuts were large: a four-bedroom home in Bang Tao from ฿380,000 to ฿250,000 a month, and a five-bedroom in Pa Klok from ฿290,000 to ฿250,000. The median of the continuing rents is ฿130,000 on both dates, and their combined monthly asking rent fell by 0.04%.
On the sale side the six changes were all upward, by between 9% and 35%. Changes of that size can be an owner re-pricing or a listing being corrected, and our records do not tell the two apart, so we read them as six listings and not as a trend. The median of the 730 continuing sale listings is ฿19.9m on both dates.
"Left the book" covers homes that were let, sold or withdrawn, and we cannot say which. "New to the book" means new to us, not necessarily new to the market.
Rents: a still month before the high season
| District | 3-bed median rent | Listings | 5 October |
|---|---|---|---|
| Bang Tao | ฿150,000 | 345 | ฿150,000 (347) |
| Kamala | ฿150,000 | 21 | ฿150,000 (21) |
| Thalang | ฿126,500 | 54 | ฿126,500 (54) |
| Rawai | ฿120,000 | 183 | ฿120,000 (185) |
| Chalong | ฿100,000 | 102 | ฿100,000 (103) |
| Pa Klok | ฿99,000 | 16 | ฿99,000 (16) |
| Kathu | ฿90,000 | 29 | ฿90,000 (30) |
| Ko Kaeo | ฿87,500 | 56 | ฿87,500 (56) |
Every district three-bedroom median is where it was a month ago. These medians cover every three-bedroom rental in the district, not villas alone. Island-wide, the ladder by size has not moved either: ฿50,000 a month for one bedroom (27 listings), ฿90,000 for two (218), ฿120,000 for three (844), ฿170,000 for four (515), ฿250,000 for five (160) and ฿290,000 for six (45). Of the 1,829 rentals, 1,800 carry a twelve-month minimum lease.
The rental book is slightly smaller, 1,829 against 1,848, because 25 homes left and six arrived. The ones that left were cheaper than average, with a median of ฿115,000, and the six newcomers were dearer, at ฿230,000. That is why the median of the whole rental book edged up from ฿130,000 to ฿135,000 while the like-for-like median stayed at ฿130,000: another composition effect, and a small one.
The sale side: 396 new listings, and a new median
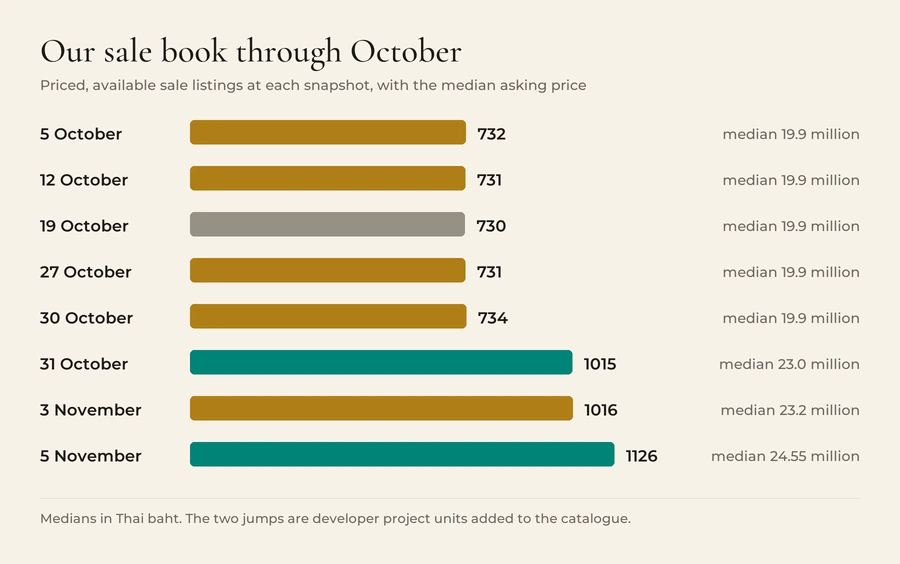
For most of October the sale book sat at 730 to 734 listings. Then it rose by 281 on 31 October and by another 110 on 5 November. Of the 396 new sale listings, 395 are units in developers' projects: 157 projects in all, 119 of which had nothing on our book before. They are villas almost entirely (374), with 18 townhouses and four houses. More than half are in Bang Tao (203), followed by Thalang (54), Rawai (48), Chalong (28) and Ko Kaeo (27).
Our catalogue does not record whether each of these units is finished or still being built, so we have not split them that way. A buyer should ask that first about any of them, and read our guide to buying off-plan and protecting a deposit before paying one.
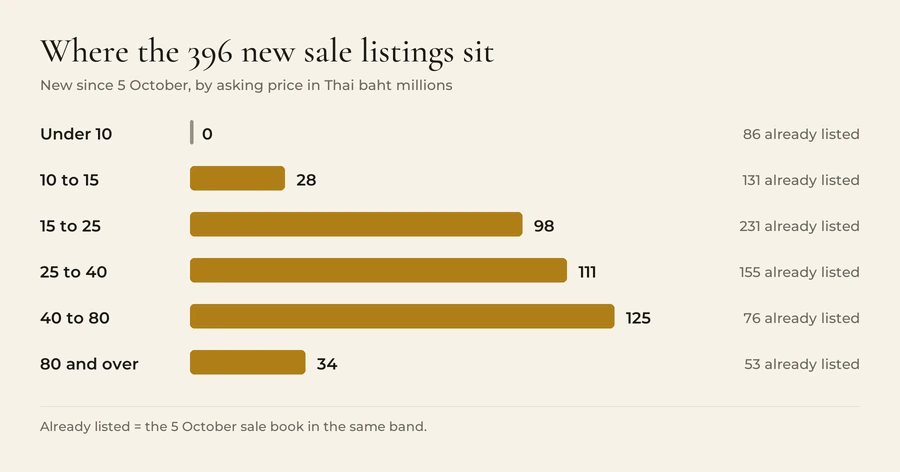
| Asking price | 5 October | New | 5 November |
|---|---|---|---|
| Under ฿10m | 86 | 0 | 86 |
| ฿10m to ฿15m | 131 | 28 | 159 |
| ฿15m to ฿25m | 231 | 98 | 326 |
| ฿25m to ฿40m | 155 | 111 | 266 |
| ฿40m to ฿80m | 76 | 125 | 202 |
| ฿80m and over | 53 | 34 | 87 |
The new stock sits higher than the book it joined. Its median asking price is ฿34.95m, against ฿19.9m for the October book. Like for like on size it is still dearer: new three-bedroom units have a median of ฿25.0m (163 listings) against ฿18.9m for the three-bedroom homes already listed (286), and new four-bedroom units ฿40.3m (149) against ฿27.95m (199). Per square metre of built area, the new units' median is about ฿84,000 against about ฿76,300 for the October book (712 listings with a usable built area).
The ฿40m to ฿80m band more than doubled, from 76 listings to 202. Nothing arrived under ฿10m, so that band is still 86 listings and has shrunk from 11.7% of the sale book to 7.6%.
District medians: the mix, not the market
| District | 5 October | 5 November, whole book | 5 November, same listings only |
|---|---|---|---|
| Bang Tao | ฿25.65m (260) | ฿30.5m (462) | ฿25.7m (259) |
| Thalang | ฿20.4m (58) | ฿22.1m (112) | ฿20.4m (58) |
| Chalong | ฿16.9m (77) | ฿19.8m (105) | ฿16.9m (77) |
| Ko Kaeo | ฿15.95m (30) | ฿24.95m (56) | ฿15.9m (29) |
| Rawai | ฿15.9m (179) | ฿17.9m (227) | ฿15.9m (179) |
Read the last two columns together. Ko Kaeo's median rose 56% on the whole book and fell by ฿50,000 on the listings that were there in October. Bang Tao's rose 19% and, like for like, by 0.2%. A report this winter that says "Phuket villa prices up 20%" may be measuring nothing more than a catalogue that took on a batch of new projects. Ask what is in the sample before you believe the headline, including ours.
Where the supply is
Bang Tao is now 40.5% of our book, up from 38.8% in October, because half the new project units are there. Rawai is 20.8% and Chalong 10.6%. Our district pages carry the live counts, and the Phuket property price index publishes price per square metre by district on the same catalogue.
The demand side
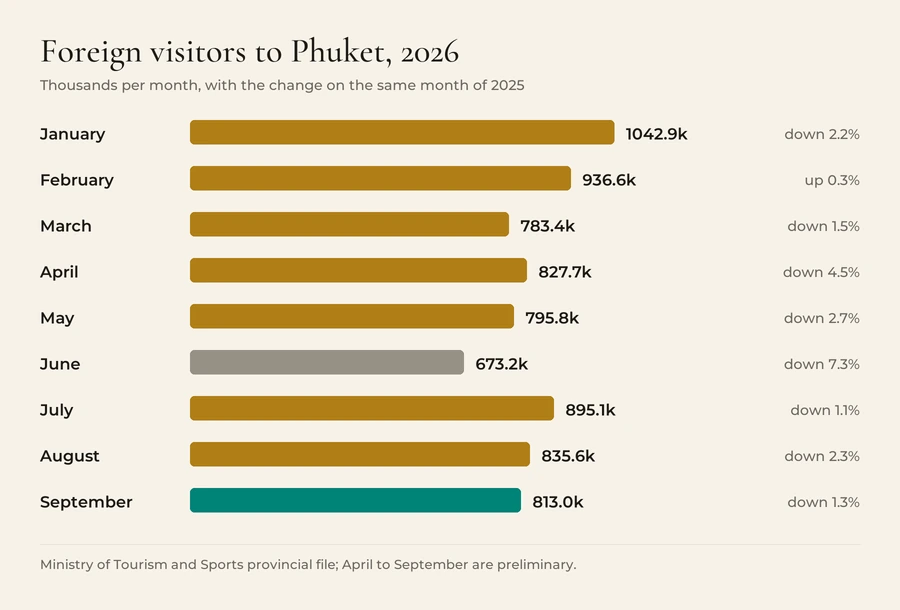
The Ministry of Tourism and Sports' provincial file now runs to September. Phuket received 812,970 foreign visitors in September, 1.3% fewer than a year earlier, and 7.60 million over the first nine months against 7.79 million: down 2.4%. September's accommodation occupancy was 66.3%, against 65.8% a year earlier. The file counts visitors staying in the province, not border arrivals.
The national arrivals file has reached October, and October was weak: 2.27 million international arrivals against 2.57 million a year earlier, down 12.0%. Over ten months Thailand is down 4.6%, at 25.46 million. China, the one large market growing this year, fell 13.6% in October, although it is still up 12.4% over ten months. Malaysia is down 16.3% for the year and South Korea 26.9%. The European, American, Australian and Russian markets moved far less: Russia down 0.3% over ten months, the United States up 0.9%, the United Kingdom down 3.4%, Germany down 2.9% and Australia down 0.7%. Phuket's own October figure is not out yet.
A visitor count measures holidays, not twelve-month leases or purchases, and we would not read one as a forecast for the other. What it does show is that the fall is concentrated in the regional Asian markets, not the long-haul ones.
The official housing data
The Bank of Thailand's residential property price index, which has no Phuket breakdown, now runs to September. Its southern-region single-detached-house series stood at 150.6, against 151.0 in August and 152.6 in July, on a 2011 base of 100. It is a regional index built from mortgage-loan data, and two small falls in a row are the extent of the signal.
The Real Estate Information Center has not yet published its third-quarter second-hand housing release; its most recent releases, up to 26 October, cover Bangkok and other regions. The latest Phuket figures are therefore still the second quarter's: 1,905 second-hand homes transferred, up 4.8% on a year earlier, and 2,650 listed for sale, up 21.1%. More stock coming to market than transactions to absorb it is the same direction our own book took in October.
Money
On 28 October the Bank of Thailand's Monetary Policy Committee held the policy rate at 1.00%, unanimously, with one member absent. The Bank now projects growth of 2.4% in 2026 and 2.1% in 2027, and headline inflation averaging 2.1% this year, pushed up by energy prices and El Niño before falling back. Its statement says foreign arrivals are "expected to decline amid higher oil prices", and that the baht has weakened against the US dollar. For a buyer bringing dollars into Thailand, a weaker baht means a price in baht costs fewer dollars than it did; we make no forecast about where the rate goes next.
What it means
If you are renting. Landlords on our book did not move going into the high season: four changes in 1,823 rents, three of them cuts. The asking rent is the rent you will be quoted, and the room to negotiate is in the terms (lease length, deposit, what is included) rather than the monthly figure. Browse villas for long-term rent, and read our six warning signs before you pay a deposit first.
If you are buying. There is a great deal more choice above ฿15m than there was a month ago, and none at all added below ฿10m. Resale sellers did not cut, so a well-argued offer below asking is still a conversation and not a given. Between a home already on our book and a newly added project unit of the same size, the gap is wide: about ฿6m at the three-bedroom median. Our best-value list ranks the book on price per square metre, and the sale quiz narrows villas for sale to your budget and district in a minute.
If you own a villa. Your competition grew sharply in October, and it grew above the median. An owner asking ฿15m to ฿25m now sits beside 98 newly added project units in the same band, and a buyer will compare the two directly. If you want to sell or let to a long-term tenant, list it with us and we will price it against this book.
We will run this again at the start of December with the same method, against this month's snapshot. Browse everything available now, the projects behind the new listings, or talk to the desk. The quarter that came before is in our Q3 villa market report.